
Will tech recover from its AI spree?

 S&P 500 -0.30% to 7,720.39 US 10-year yield -5.6 basis points to 4.939% Spot gold -1.16% to $4,019.71 an ounce DXY -0.23% to 101.88
What to look out for today
Companies reporting on Friday, 30th October: Abbvie, Chevron, ExxonMobil, AstraZeneca, BP, Sanofi, Colgate-Palmolive, Imperial Oil, Dominion Energy, LyondellBasell Industries, Exelon
Key data to move markets today
EU: French GDP, French CPI, Spanish GDP, Spanish Harmonised Index of Consumer Prices, German Harmonised Index of Consumer Prices, German Unemployment Change, German Unemployment Rate, German GDP, German CPI, Italian GDP, Italian CPI, Eurozone GDP, Eurozone Unemployment Rate and a speech by ECB Chief Economist Philip Lane
USA: Employment Cost Index, Chicago PMI and speeches by St Louis Fed President Alberto Musalem and San Francisco Fed President Mary Daly
JAPAN: BoJ Interest Rate Decision, BoJ Monetary Policy Statement, BoJ Outlook Report and BoJ Press Conference
Global Macro Updates
A sudden change at the ECB. ECB President Christine Lagarde shocked markets on Thursday by announcing that she would be leaving her post on 7 February 2027. She had been expected to complete her term in October 2027. The ECB is set for a shake up in the first half of 2027 with Lagarde’s early departure as well as the departure of ECB Executive board member Isabel Schnabel and ECB Chief Economist Philip Lane.
President Lagrade explained her decision, saying the reason is because “I want to have the freedom of speech, the freedom of expression, and the freedom to engage on matters that are not monetary policy matters... In relation to many corners of the world, not just European corners, not just Europe, I think that my voice can help, my action can help, in relation to principles that are dear to my heart.”
US growth steams ahead. The US economy grew faster than expected, with GDP increasing at a 3.4% annualised rate last quarter fuelled by resilient consumer spending and AI driven business investment.
On the inflation front, the Personal Consumption Expenditures Price Index — the Fed's preferred inflation gauge — climbed 0.5% last month, after an unrevised 0.3% rise in August, according to the Commerce Department's Bureau of Economic Analysis. The increase was in line with economists' expectations. In the 12 months through September PCE inflation advanced 3.6% after an unrevised 3.4% rise in August. The Core PCE Price Index rose 0.3% over the month after an upwardly revised 0.3% gain in August. Core PCE inflation increased 3.1% year-on-year in September after an unrevised 3.0% rise in August.
US Stock Indices
Dow Jones Industrial Average -0.25%
Nasdaq 100 -1.38%
S&P 500 -0.30%, with 8 of the 11 sectors of the S&P 500 up
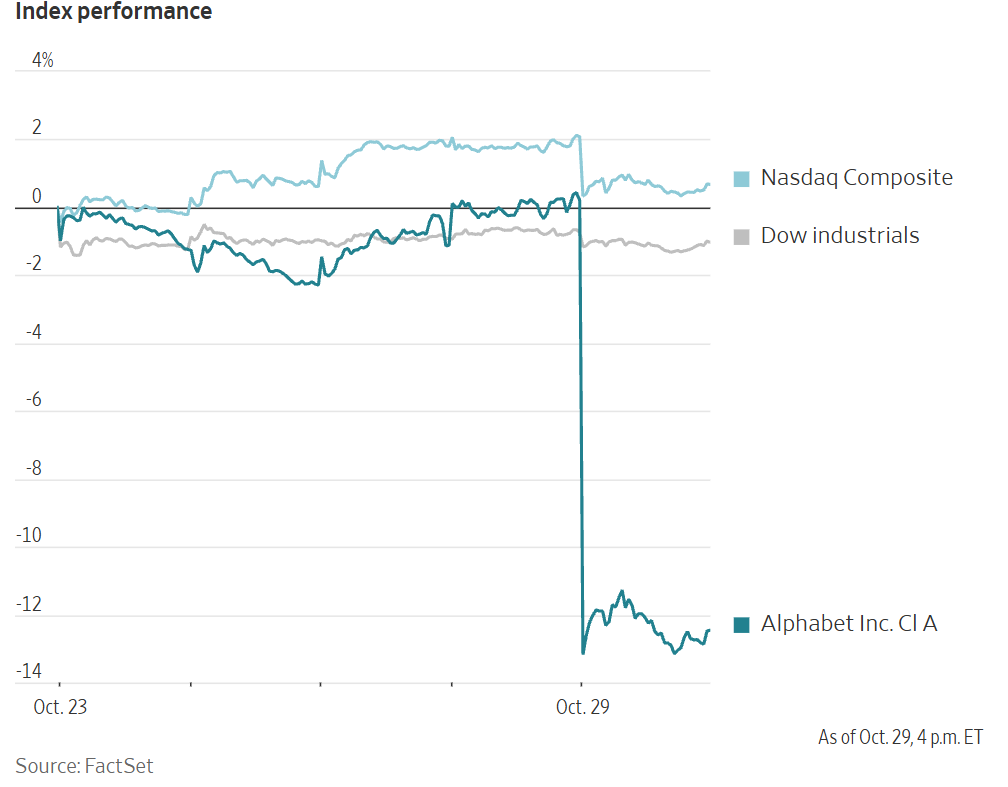
Equities markets were lower onThursday, as tech stocks slid following Alphabet’s worse than expected search and advertising sales, causing investors to reassess the AI spending spree. Alphabet had its worst day ever, losing about half a trillion dollars of market value after its earnings disappointed investors. It finished the day almost 13% down, surpassing its previous biggest one-day loss of 11.6% in 2020. Alphabet’s market value drop is the second-biggest in Wall Street history, after Nvidia’s $593bn loss in January 2025.
Amazon’s and Intel’s results also raised fears about the buildout of the AI economy, with their share price falling almost 7% and over 22% respectively in post market trading.
Semiconductor stocks ended their four-day winning streak, falling -1.4% as investors tried to distinguish between companies able to fund their AI ambitions and those needing to borrow to realise those goals.
The Dow Jones Industrial Average fell 132.54 points, or -0.25%, to 52,342.56, the S&P 500 declined 23.59 points, or -0.30%, to 7,720.39 and the Nasdaq Composite lost 365.13 points, or -1.37%, to 26,184.72.
In corporate news, Microsoft is planning to raise about $25 billion through its first US investment-grade bond sale in more than nine years, two sources familiar with the matter told Reuters.
According to Bloomberg news, Anthropic PBC is SpaceX’s largest single customer, a person familiar with the matter said, accounting for more than a third of the revenue for Elon Musk’s AI, satellite and rocket venture during the third quarter of this year.
In a deal valued at $17 billion, DoorDash said it would buy Instacart as it increases its push into the fast-growing US grocery delivery market.
Reddit was reported to plan to limit access to its online user forums to users with accounts in an attempt to increase engagement and improve its advertising business.
Corporate Earnings Reports
Posted on Thursday, 29 October from The Pulse, our real-time AI-driven news tool. Available exclusively on the EXANTE Web Platform
Amazon reported third-quarter net sales up +12% y/y to $201.9bn vs $202.25bn expected, alongside EPS of $1.89 vs $1.97 expected. Operating income rose to $28.1bn, driven by AWS revenue accelerating up +39.3% y/y to $46.0bn, reaching an annualised run rate of $184bn. Quarterly capital expenditure reached $77.3bn, contributing to a trailing twelve-month free cash flow deficit of -$42.4bn, while full-year 2026 capex remained guided at approximately $220bn. Fourth-quarter revenue guidance was set at $240.0bn to $247.0bn. In regulatory developments, the Federal Communications Commission approved Amazon's $11.5bn acquisition of Globalstar. AWS also secured an infrastructure agreement exceeding $2bn with Verizon, and the group enacted job reductions in its devices division. Chief Executive Andy Jassy stated that AWS is projected to grow over +40% annually across both 2027 and 2028.
Eli Lilly reported Q3 2026 revenue of $24.4bn vs $22.52bn expected, up +39% y/y, and adjusted EPS of $7.48 vs $5.59 expected. Performance was driven by Mounjaro revenue reaching $10.7bn, up +65% y/y, and Zepbound sales of $5.35bn, up +49% y/y. The firm raised its full-year 2026 revenue guidance to between $91.0bn and $92.0bn, up from prior guidance of $85.0bn to $87.0bn, with adjusted EPS projected at $35.00 to $36.00. Strategically, Lilly completed acquisitions of AtaiBeckley and Merida Biosciences, whilst trial data showed retatrutide exceeded Ozempic in weight loss. Bernstein SocGen Group maintained an Outperform rating, lifting its price target to $1450 from $1385. Chief Executive Dave Ricks stated that strong demand across metabolic portfolios drove the quarter beyond expectations.
Coinbase reported Q3 2026 revenue of $1.22bn vs $1.23bn expected, down -35% y/y, and EPS of $2.51 vs -$0.06 expected. Net income reached $718.7mn, driven by a $715mn gain on crypto assets, while prediction markets surpassed $200mn in annualized revenue. The company reduced its full-year 2026 adjusted expense guidance to $4.15bn-$4.30bn and projected Q4 subscription and services revenue between $550mn and $630mn. Chief Executive Officer Brian Armstrong announced plans to sell up to $1.31bn in shares through October 2027 at designated price targets while maintaining the majority of his holding.
Mastercard reported Q3 2026 adjusted EPS of $5.31 vs $5.16 expected, up +21% y/y, with net revenue of $9.8bn vs $9.65bn expected, up +14% y/y. Value-added services and solutions revenue rose +19% y/y, payment network revenue grew +11% y/y, and cross-border volume rose +11% y/y. The company repurchased 5.3mn shares for $3.0bn and distributed $763mn in dividends, whilst reiterating full-year 2026 currency-neutral net revenue growth at the high end of low double digits. The Chief Executive Officer noted that the firm delivered a strong quarter and is actively building future commerce infrastructure through agentic commerce and its global money platform. Separately, Mastercard partnered with central banks on Singapore's BLOOM cross-border settlement initiative.
Intel reported Q3 2026 revenue of $16.51bn vs $16.54bn expected, up +21% y/y, and adjusted EPS of $0.52 vs $0.41 expected, up +126% y/y. Data Centre and AI revenue rose +78% y/y to $7.32bn vs $6.67bn expected, while Client Computing revenue fell -5% y/y to $8.10bn vs $8.82bn expected. For Q4, Intel issued weak guidance, forecasting revenue of $15.0bn to $16.0bn vs $17.05bn expected and adjusted EPS of $0.25 vs $0.43 expected, citing PC market inventory corrections and supply constraints. Additionally, Intel agreed to acquire quantum software startup Classiq and expanded its enterprise AI collaboration with Oracle. Chief Executive Officer Lip-Bu Tan stated that although the company performed well in Q3, near-term manufacturing supply shortages and PC demand softness remain challenging.
Merck reported third-quarter revenue of $18.09bn vs $17.31bn expected, up +4.6% y/y, and adjusted EPS of $2.49 vs $2.07 expected, down -3% y/y. Growth was supported by Keytruda sales of $8.60bn vs $8.38bn expected and Winrevair revenue of $694mn, which surged +93% y/y. Gardasil revenue reached $2.00bn vs $1.75bn expected, while Animal Health sales recorded $1.68bn. Consequently, Merck raised its full-year 2026 revenue guidance to between $66.8bn and $67.3bn, alongside increasing adjusted EPS projections to $2.77 to $2.82. In a separate update, Chief Executive Rob Davis stated that the company is expediting the regulatory submission of its cancer vaccine co-developed with Moderna, aiming for approval in 2027.
Caterpillar reported Q3 2026 revenue of $20.7bn vs $20.54bn expected, representing an increase of +17% y/y, and adjusted EPS of $7.20 vs $7.08 expected, up +45% y/y. Power & Energy revenue rose +18% y/y to $8.8bn, Construction Industries climbed +18% y/y to $8.0bn, and Resource Industries grew +15% y/y to $4.6bn, while the total backlog reached a record $78.1bn. Operating cash flow reached $4.4bn, enabling $2.0bn in capital returns to shareholders. Caterpillar maintained its full-year revenue growth guidance at mid-to-high teens, forecasting a roughly $1bn y/y sales headwind from construction dealers cutting inventory by $1.6bn in Q4. Chief Executive Joe Creed remarked that results reflected durable end markets and record order backlogs, while noting that production capacity in Power & Energy remained fully constrained.
Gilead Sciences reported Q3 2026 revenue of $8.3bn up +7% y/y vs $7.81bn expected, while adjusted EPS reached $2.55 up +3% y/y vs $2.19 expected. GAAP EPS stood at $1.94 and operating cash flow reached $5.0bn. For full-year 2026, the company raised product sales guidance to between $31.0bn and $31.3bn from prior expectations of $30.1bn to $30.4bn. However, full-year adjusted EPS guidance was lowered to between -$1.20 and -$0.85 vs -$0.46 expected, driven by a $12.4bn acquired IPR&D charge representing an approximate $9.88 per share impact. The board declared a Q4 2026 dividend of $0.82 per share. Management stated that robust performance enabled another upward revision to full-year base business revenue guidance.
Starbucks reported Q4 2026 results after the close, posting adjusted EPS of $0.80 vs $0.71 expected, up +54% y/y, and revenue of $9.14bn vs $9.23bn expected, down -4% y/y. Global comparable store sales rose +7.2% vs +6.2% expected, supported by US comparable sales up +7.7% vs +6.7% expected, whilst international comparable sales grew +0.9% vs +3.2% expected. For fiscal 2027, the company forecast adjusted EPS of $3.15 to $3.25 vs $3.14 expected. Operationally, Starbucks announced the resumption of share buybacks, converted Chinese retail operations into a licensed joint venture, and outlined plans to pilot drive-thru artificial intelligence by 2027. Chief Executive Officer Brian Niccol stated that the turnaround strategy had transitioned into the company's core growth plan.
Altria reported its Q3 2026 financial results, with net revenue excluding excise taxes rising +3.6% y/y to $5.4bn vs $5.31bn expected. Adjusted EPS rose +4.8% y/y to $1.52 vs $1.51 expected. By segment, Smokeable Products revenue increased +0.8% y/y to $5.4bn, while Oral Tobacco Products fell -0.1% y/y to $688mn. Altria raised its full-year 2026 adjusted EPS guidance to a range of $5.66 to $5.74 vs the prior $5.61 to $5.72 outlook. The company returned capital by paying $1.7bn in dividends, completing $400mn in share repurchases, and expanding its share buyback programme by $1bn. Management stated that strong performance across the first nine months and confidence in their plan enabled the earnings guidance increase alongside significant cash returns to shareholders.
European Stock Indices
CAC 40 +1.05%
DAX +1.31%
FTSE 100 +0.26%
According to LSEG I/B/E/S data, Q3 earnings are expected to increase 23.6% from Q3 2026. Excluding the Energy sector, earnings are expected to increase 9.8%. Third quarter revenue is expected to increase 13.6% from Q3 2026. Excluding the Energy sector, revenues are expected to increase 6.2%.
Of the 144 companies in the STOXX 600 that have reported earnings to date for Q3 2026, 54.2% reported results exceeding analyst estimates. Of the 180 companies in the STOXX 600 have reported revenue to date for Q3 2026, 61.1% reported revenue
exceeding analyst estimates.
During the week of 2 November, 65 companies are expected to report quarterly earnings.
Commodities
Gold spot -1.16% to $4,019.71 an ounce
Silver spot -3.48% to $52.10 an ounce
West Texas Intermediate -0.76% to $102.00 a barrel
Brent crude -0.38% to $114.88 a barrel
Gold prices fell on Thursday on stronger than expected US economic data and rising expectations of a Fed interest rate hike in December after the Fed held rates steady on Wednesday. Spot gold fell -1.16% to $4,019.71 an ounce.
Spot silver declined -3.48% to $52.10 per ounce.
Oil prices fell on Thursday after The Wall Street Journal reported US Vice President JD Vance had sent a letter to Iranian Security Council chief Mohsen Rezaei in an effort to revive peace negotiations. In addition, according to Reuters, Qatari mediators presented Iran with a new draft deal to end the war, though a senior Iranian official dismissed what had been presented as unacceptable.
Brent settled at $114.88 per barrel, down -0.38%, or $0.44, on the day. WTI crude settled down -0.76%, or $0.78, at $102.00 a barrel.
Also on Thursday the US government said that oil companies have agreed to borrow about 40 million barrels of crude from the Strategic Petroleum Reserve. The Energy Department said it awarded contracts on 28 October for nearly 16.8 million barrels.
Note: As of 4 pm EDT 29 October 2026
Currencies
EUR +0.25% to $1.118
GBP +0.38% to $1.3375
Bitcoin -2.70% to $79,081.15
Ethereum -4.18% to $2,259.66
The US dollar was down on Thursday in part due to investors assessing the dovish tone from Fed Chair Kevin Warsh on Wednesday and falling Treasury yields. The dollar index, which measures the greenback against a basket of currencies including the yen and the euro, fell -0.23% to 101.88.
The euro edged higher on Thursday after the ECB, as widely expected, kept interest rates unchanged and the ECB signalled that a December rate hike remains firmly on the table due to rising energy costs. The euro fell to its lowest against the dollar since May, but was up +0.25% at $1.118. The euro weakened -0.21% against the pound to 0.8354 pence.
The dollar weakened -0.07% against the Japanese yen to ¥157.69 per dollar. The BoJ is widely expected to hold rates at its policy meeting on Friday.
Sterling was +0.38% against the dollar to $1.3375 as markets assessed the UK autumn budget amid rising expectations for a BoE interest rate hike in November.
Fixed Income
US 10-year Treasury -5.6 basis points to 4.979%
German 10-year Bund -1.1 basis points to 3.367%
UK 10-year Gilt -3.8 basis points to 5.296%
US Treasury yields fell on Thursday as investors assessed US inflation data and more AI-related volatility in equities.
The yield on benchmark US 10-year notes fell -5.6 basis points to 4.979%. The 30-year bond yield fell -3.8 basis points to 5.300%. The 2-year note, which typically moves in step with Fed interest rate expectations, fell -12.4 basis points to 4.594%.
The US 2s10s yield spread widened to 38.5 bps from 27.6 bps on Wednesday.
Rate futures priced in a 76.1% probability of a 25 bps hike at the Fed’s December meeting, up from 73.3% a week earlier, according to CME’s FedWatch tool.
Eurozone government bond yields also fell on Thursday following the ECB’s decision to hold rates. Although ECB President Lagarde played down the risk that inflation is broadening beyond energy, she stressed that risks are skewed to the upside. Markets are pricing in an 85% chance of a rate rise in December and another rate rise in 2027.
Germany’s 10-year Bund yield fell -1.1 bps to 3.367%. The two year Schatz fell -6.1 bps to 3.065%, while at the long end, the 30-year Bund yield rose +1.7 bps to 3.701.
France’s 10-year OAT yield was -1.6 bps to 4.906%. Its spread over 10-year Bunds stood at 153.9 bps.
Italy’s 10-year BTP yield was -3.0 bps to 4.469%. Its spread over 10-year Bunds stood at 110.2 bps.
Note: As of 4 pm EDT 29 October 2026
While every effort has been made to verify the accuracy of this information, EXT Ltd. (hereafter known as “EXANTE”) cannot accept any responsibility or liability for reliance by any person on this publication or any of the information, opinions, or conclusions contained in this publication. The findings and views expressed in this publication do not necessarily reflect the views of EXANTE. Any action taken upon the information contained in this publication is strictly at your own risk. EXANTE will not be liable for any loss or damage in connection with this publication.
هذه المقالة متاحة لأغراض معلوماتية فقط، ولا ينبغي اعتبارها عرضًا أو التماسًا لعرض شراء أو بيع أي استثمارات أو خدمات ذات صلة يمكن الإشارة إليها هنا. ينطوي التداول في الأدوات المالية على مخاطر كبيرة من الخسارة وقد لا يكون مناسبًا لجميع المستثمرين. الأداء السابق ليس مؤشرًا موثوقًا به للأداء المستقبلي.
 العودة إلى جميع الرؤى




أنشأها المتخصصون. للمحترفين.
