

The UK and Europe continue to stay afloat
STOCK-INDEX PERFORMANCE
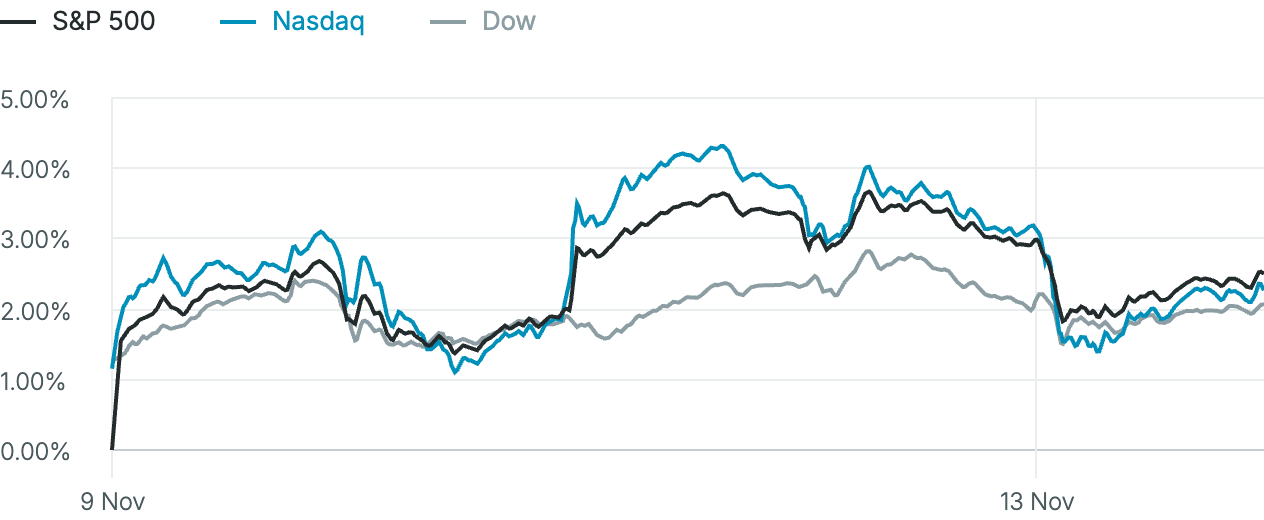
Source: FactSet, as of 13 November, 4 PM ET.
An uneasy expansion
Last week’s gas prices climbing above €85/MWh amid tanker attacks in the Strait of Hormuz and limited progress towards a US – Iran resolution reinforced hawkish ECB rhetoric. ECB Chief Economist Philip Lane suggested a December rate increase would be prudent if incoming data remained unchanged, warning inflation could exceed 4% by year-end. BoE Deputy Governor Clare Lombardelli described December and February as live meetings.
However, stronger growth provided some reassurance. Eurozone Q3 GDP expanded 0.4% q/o/q, double the rate of expectations, while UK output rose 0.7%, its strongest quarterly performance in over two years. Technology and AI investment attracted attention as increasingly important UK growth drivers. Nevertheless, slower hiring, deteriorating housing sentiment and higher mortgage rates highlighted underlying vulnerabilities. KPMG warned that depleted household and corporate financial buffers could leave the recovery exposed to further energy shocks.
Meanwhile, Germany’s 2027 budget envisages €210.4 billion in new borrowing, while French political and fiscal uncertainty continues to pressure sovereign spreads.
Equities
Chip and data-centre stocks finished the week under pressure, but the major US indices still rose, supported by a strong earnings season. For the week, the Nasdaq composite gained 2.27%, the S&P 500 rose 2.51% and the Dow Jones Industrials added 2.07%.
The AI trade faces two major tests this week. Nvidia reports earnings on Tuesday, when CFO and interim CEO Colette Kress will be asked about the web of financing deals Huang struck. Anthropic’s IPO is expected on Thursday.
- S&P 500 7,561.67 -0.40%
- Nasdaq Composite 25,136.27 -0.91%
- Dow Jones Industrial 52,347.55 +0.10%
- DAX 26,749.95 -0.08%
- CAC 40 8,368.91 +0.09%
- FTSE 100 10,902.56 +0.36%
Currencies
The US dollar had its strongest weekly gain in two months on Friday and stayed near a 19-month high. The euro touched its weakest level against the dollar since April 2025, marking a fourth straight weekly loss. The yen posted its largest weekly decline since September. Japanese Finance Minister Satsuki Katayama said on Friday that the government would respond appropriately to currency volatility.
- DXY 103.41 +0.23%
- EUR/USD $1.1021 -0.30%
- GBP/USD $1.3215 -0.15%
- USD/JPY ¥159.66 -0.11%
- Bitcoin $68,351.05 -4.40%
- Ethereum $1,926.98 -4.44%
Fixed Income
Yields dipped briefly on Friday after October US producer prices came in below economists' expectations.
However, the US 2-year Treasury yield rose 34.0 bps over the week. The 10-year yield rose 27.8 bps over the week, the biggest weekly gain since April 2025. According to CME Group's FedWatch Tool, Fed funds futures put a 5.0% probability on a 50 bps hike at the FOMC December meeting, up from zero a week earlier.
German government bond yields had their biggest weekly rise in two months as traders raised bets on ECB rate hikes.
The 10-year Bund yield rose 13.0 bps over the week. The 2-year yield rose 16.6 bps.
ESTR forwards now imply the ECB deposit rate will rise from the current 2.50% to about 3.25% by late 2027, up from the 3.00% priced the prior week.
- US Treasury 10-year +1.1 bps 5.145%
- German Bund 10-year +4.0 bps 3.398%
- UK Gilt 10-year +4.2 bps 5.344%
- France OAT 10-year +8.5 bps 4.921%
- Italy 10-year +5.6 bps 4.399%
Commodities
Spot gold rose 0.14% on Friday, having briefly hit a session high of $3,922.97 when US Producer Price Index data was released. It fell to its lowest level in a year last week after hotter-than-expected inflation data, rising US Treasury yields, and a stronger dollar.
WTI and Brent fell last week as the US appeared set to avoid military strikes on Iran and maintain its naval blockade and economic pressure. Iranian attacks on ships near the Strait of Hormuz continued, as did Houthi attacks on Saudi energy infrastructure and Riyadh. On Friday, US Central Command confirmed that the IRGC launched two one-way attack drones at Bahrain, and US forces shot both down.
OPEC estimated its October output rose by 2.0 million bpd, leaving it less than 1.5 million bpd below pre-war levels. The IEA expects faster Gulf supply growth and weaker demand to push the crude market into a global surplus in Q4. November month-to-date data shows Gulf product exports rising and Saudi crude exports exceeding pre-war levels.
China's October crude imports climbed to 9.880 million bpd, the highest monthly average since March.
- Spot Gold $3,880.30/oz +0.14%
- Spot Silver $48.73/oz -2.55%
- WTI crude $88.92 +0.27%
- Brent Crude $96.08 +0.33%
Key data to move markets today
Attention today turns to Fed Chair Kevin Warsh's speech on AI and Financial Stability at the 7th ACM International Conference on AI in Finance in Milan.
 Eurozone Industrial Production and a speech by ECB Vice President Boris Vujčić
 NY Empire State Manufacturing Index and speeches by Fed Chair Kevin Warsh, New York Fed President John Williams and Fed Governor Michael Barr
FEATURED TODAY
Fixed Income Briefing November 2026
Where do bond investors look when rates keep rising?
The Fed, ECB and Bank of England are all leaning towards more rate rises, and the US 10-year Treasury yield stands at 5.19%.
So why might bonds maturing in 2 to 5 years look more attractive than longer ones right now?
Read EXANTE’s Fixed Income Briefing to find out, by Renée Friedman, PhD, Global Head of Research.
Renée Friedman, PhD
Editor-in-Chief, EXANTE
While every effort has been made to verify the accuracy of this information, EXT Ltd. (hereafter known as “EXANTE”) cannot accept any responsibility or liability for reliance by any person on this publication or any of the information, opinions, or conclusions contained in this publication. The findings and views expressed in this publication do not necessarily reflect the views of EXANTE. Any action taken upon the information contained in this publication is strictly at your own risk. EXANTE will not be liable for any loss or damage in connection with this publication.
This article is provided to you for informational purposes only and should not be regarded as an offer or solicitation of an offer to buy or sell any investments or related services that may be referenced here. Trading financial instruments involves significant risk of loss and may not be suitable for all investors. Past performance is not a reliable indicator of future performance. Sentiments are generated automatically and are not investment advice.
 Back to all insights




Created by professionals. For professionals.
